
Butterfield Bank currently trades at $58.28 per share and has shown little upside over the past six months, posting a middling return of 3.5%. The stock also fell short of the S&P 500’s 13.5% gain during that period.
Given the weaker price action, is now a good time to buy NTB? Or should investors expect a bumpy road ahead? Find out in our full research report, it’s free.
Why Does NTB Stock Spark Debate?
Founded in 1784 as one of the oldest banks in the Western Hemisphere, Butterfield Bank (NYSE:NTB) provides banking, wealth management, and trust services to individuals and businesses in select offshore financial centers including Bermuda, Cayman Islands, and the Channel Islands.
Two Positive Attributes:
1. Projected TBVPS Growth Is Remarkable
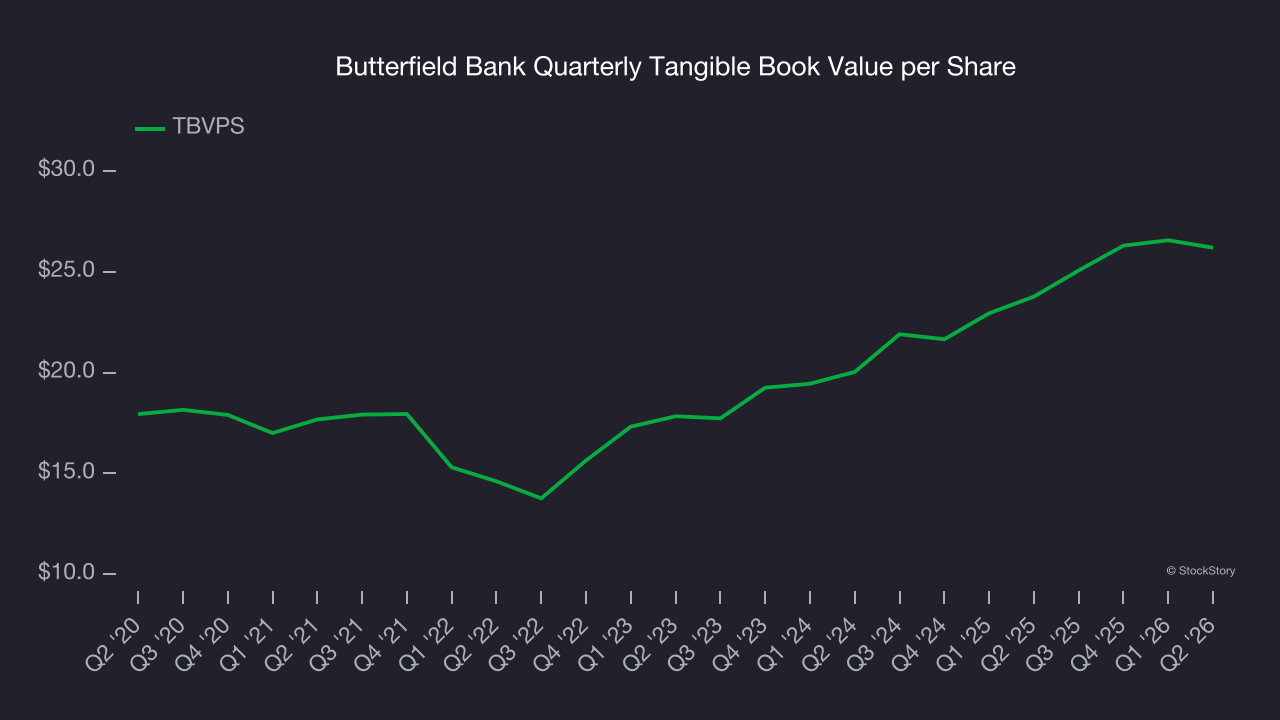
Tangible book value per share (TBVPS) growth is driven by a bank’s ability to earn more than its cost of capital through lending activities while maintaining a strong balance sheet.
Over the next 12 months, Consensus estimates call for Butterfield Bank’s TBVPS to grow by 37.2% to $35.94, an elite growth rate.
2. Stellar ROE Showcases Lucrative Growth Opportunities
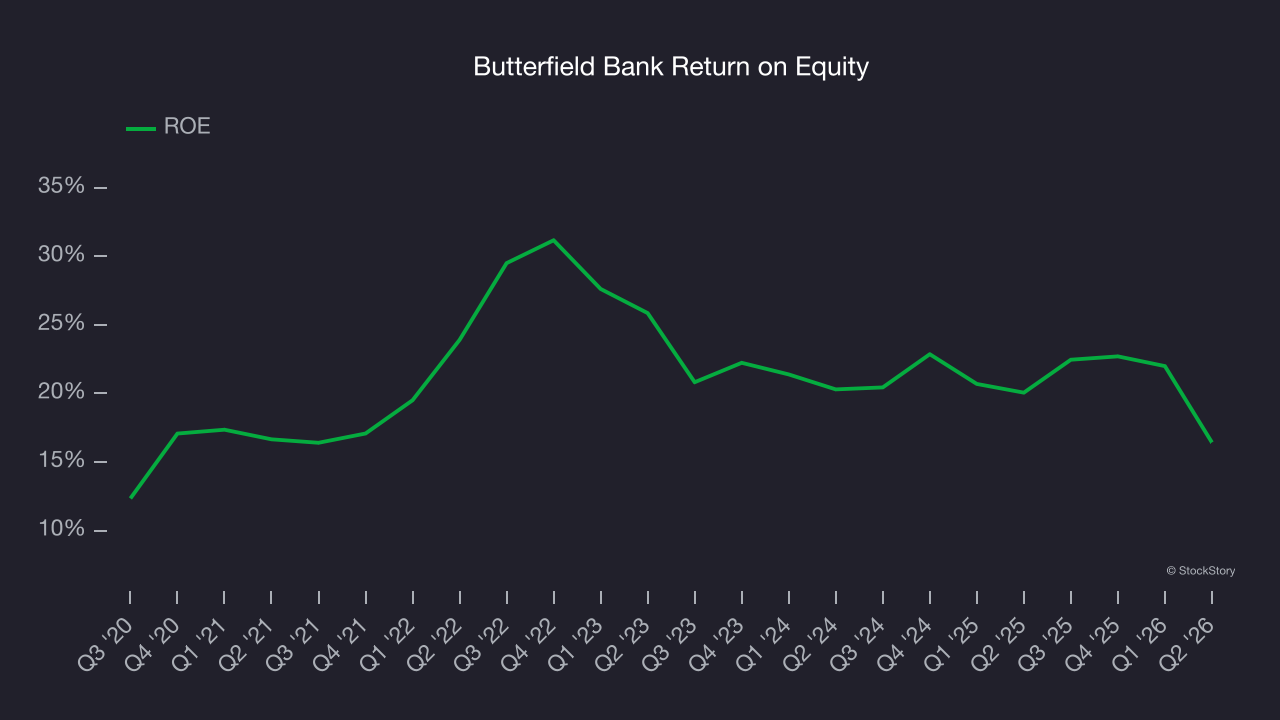
Return on equity, or ROE, tells us how much profit a company generates for each dollar of shareholder equity, a key funding source for banks. Over a long period, banks with high ROE tend to compound shareholder wealth faster through retained earnings, buybacks, and dividends.
Over the last five years, Butterfield Bank has averaged an ROE of 22.2%, exceptional for a company operating in a sector where the average shakes out around 10% and those putting up 20%+ are greatly admired. This shows Butterfield Bank has a strong competitive moat.
One Reason to Be Careful:
Net Interest Income Points to Soft Demand
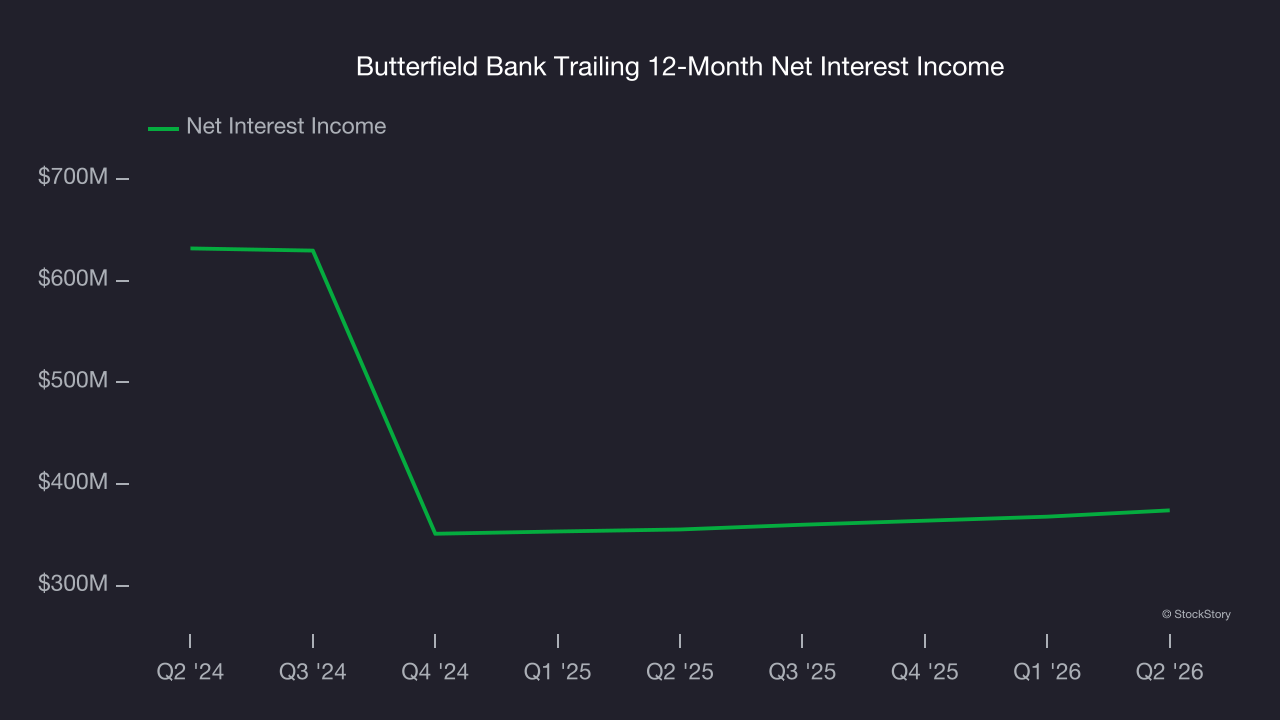
Markets consistently prioritize net interest income over non-recurring fees, recognizing its superior quality compared to the more unpredictable revenue streams.
Butterfield Bank’s net interest income has grown at a 4.5% annualized rate over the last five years, much worse than the broader banking industry and in line with its total revenue.
Final Judgment
Butterfield Bank’s merits more than compensate for its flaws. With its shares lagging the market recently, the stock trades at 1.9× forward P/B (or $58.28 per share). Is now a good time to buy? See for yourself in our full research report, it’s free.
Stocks We Like Even More Than Butterfield Bank
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.