
Brady has been treading water for the past six months, recording a small return of 1.9% while holding steady at $84.91. The stock also fell short of the S&P 500’s 15.2% gain during that period.
Is now the time to buy BRC? Find out in our full research report, it’s free.
Why Are We Positive on BRC?
Founded in 1914 and evolving through more than a century of industrial innovation, Brady (NYSE:BRC) manufactures and supplies identification solutions and workplace safety products that help companies identify and protect their premises, products, and people.
1. Long-Term Revenue Growth Shows Strong Momentum
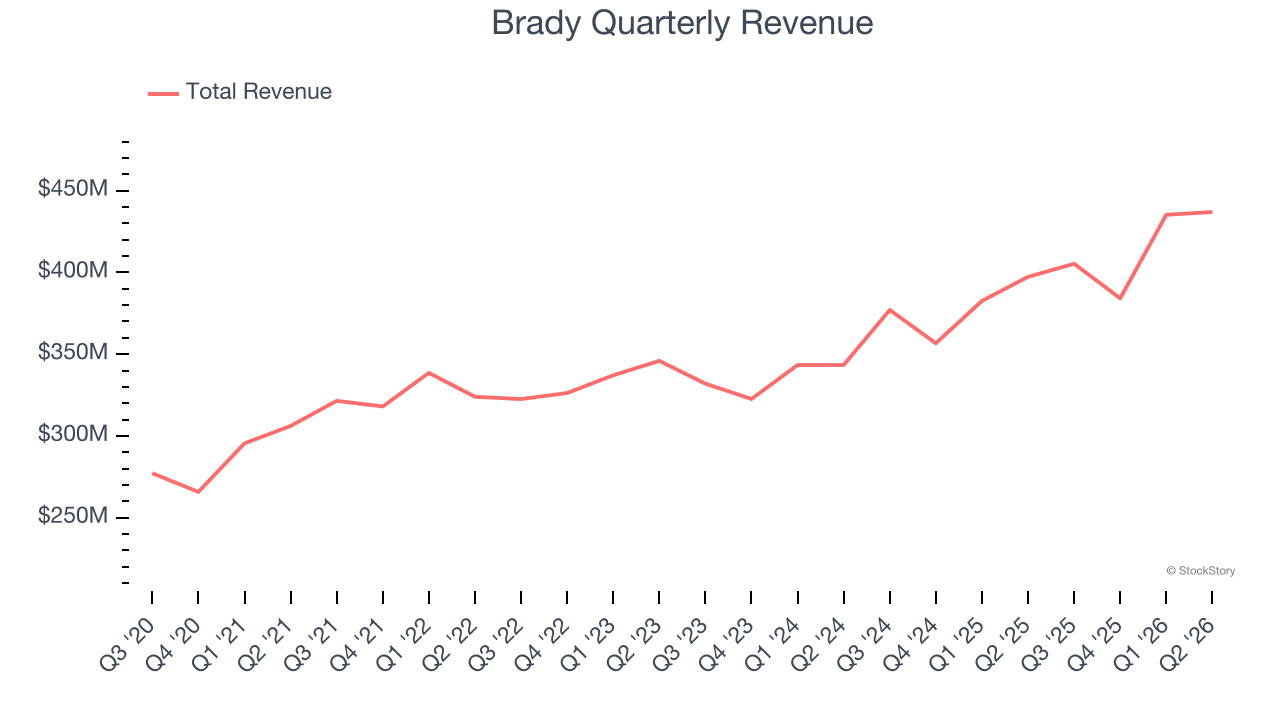
A company’s long-term sales performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Brady grew its sales at a solid 7.7% compounded annual growth rate. Its growth surpassed the average business services company and shows its offerings resonate with customers.
2. Projected Revenue Growth Is Remarkable
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite, though some deceleration is natural as businesses become larger.
Over the next 12 months, sell-side analysts expect Brady’s revenue to rise by 74%, an improvement versus its 7.7% annualized growth for the past five years. This projection is eye-popping and suggests its newer products and services will spur better top-line performance.
3. Increasing Free Cash Flow Margin Juices Financials
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
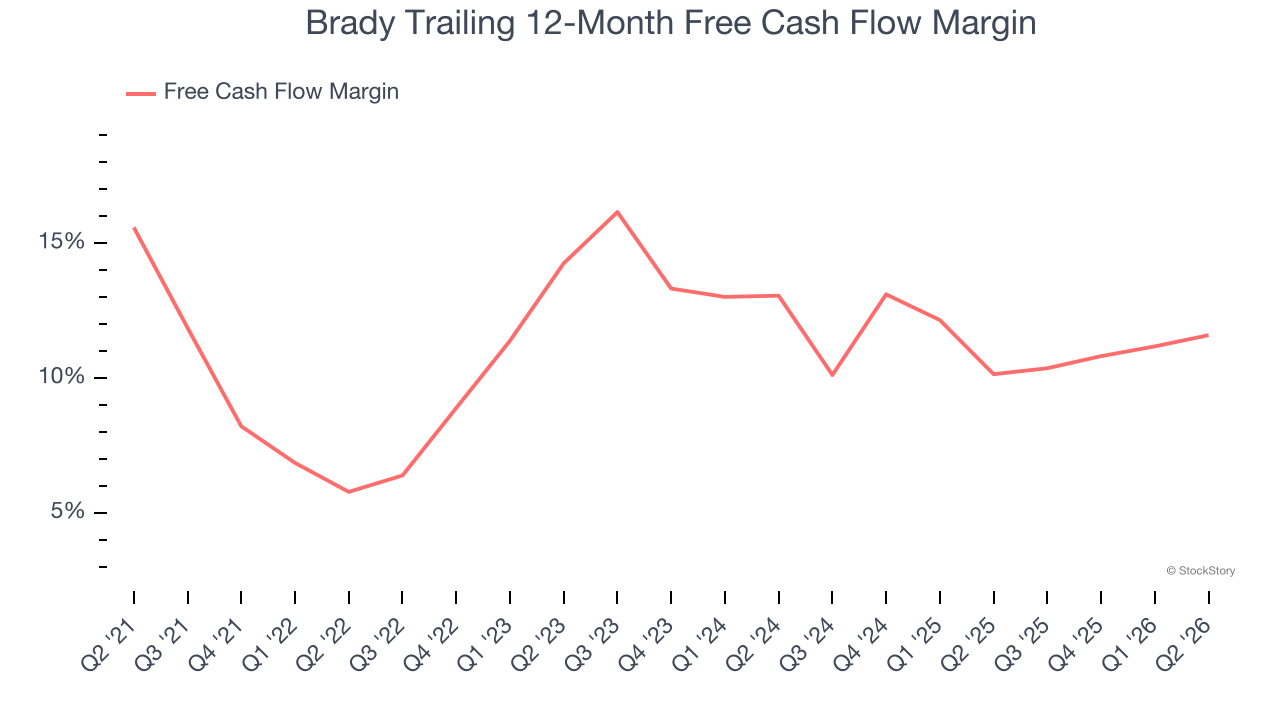
As you can see below, Brady’s margin expanded by 5.8 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Brady’s free cash flow margin for the trailing 12 months was 11.6%.
Final Judgment
These are just a few reasons why we think Brady is a high-quality business. With its shares underperforming the market lately, the stock trades at 13× forward P/E (or $84.91 per share). Is now the right time to buy? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Brady
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.