

Since October 2021, the S&P 500 has delivered a total return of 77.9%. But one standout stock has more than doubled the market - over the past five years, Plexus has surged 187% to $266.66 per share. Its momentum hasn’t stopped as it’s also gained 21.7% in the last six months thanks to its solid quarterly results, beating the S&P by 6.4%.
Is now still a good time to buy PLXS? Or is this a case of a company fueled by heightened investor enthusiasm? Find out in our full research report, it’s free.
Why Are We Positive on Plexus?
With over 20,000 team members across 26 global facilities, Plexus (NASDAQ:PLXS) designs, manufactures, and services complex electronic products for companies in aerospace/defense, healthcare, and industrial sectors.
1. Long-Term Revenue Growth Shows Momentum
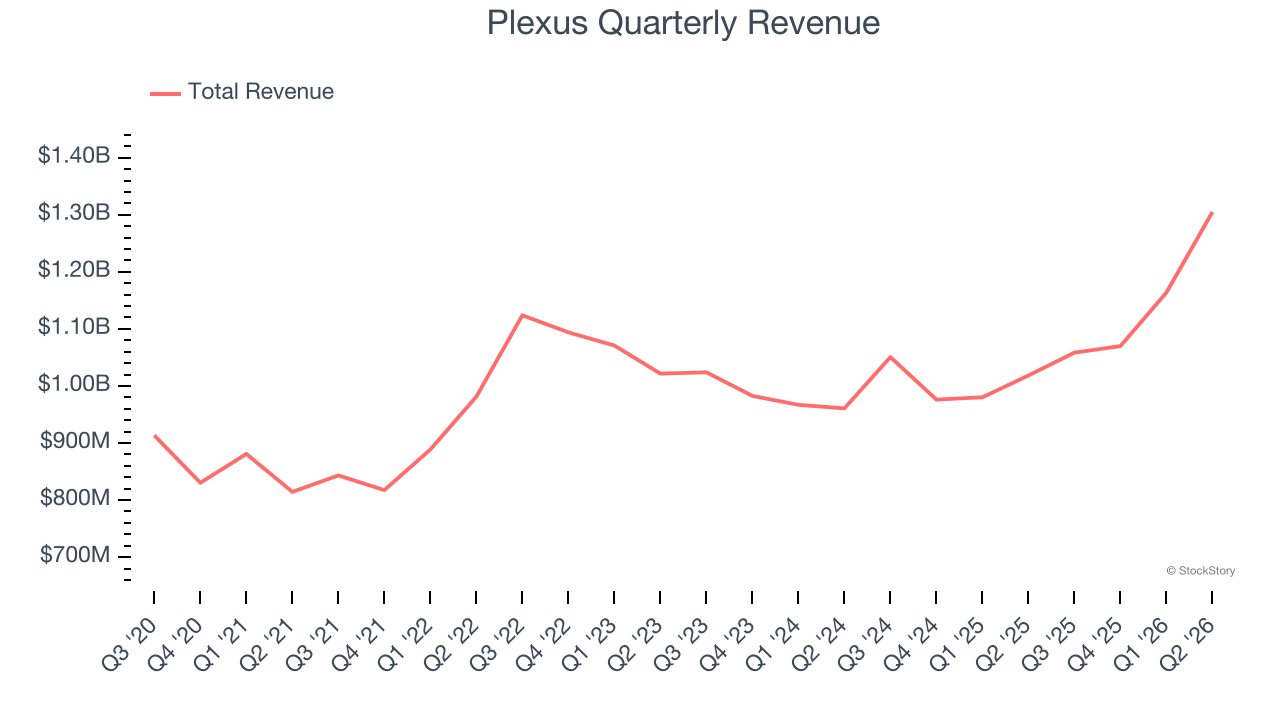
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Luckily, Plexus’s sales grew at a decent 6% compounded annual growth rate over the last five years. Its growth was slightly above the average business services company and shows its offerings resonate with customers.
2. Projected Revenue Growth Is Remarkable
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite, though some deceleration is natural as businesses become larger.
Over the next 12 months, sell-side analysts expect Plexus’s revenue to rise by 20.6%, an improvement versus its 6% annualized growth for the past five years. This projection is eye-popping and indicates its newer products and services will fuel better top-line performance.
3. Outstanding Long-Term EPS Growth
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
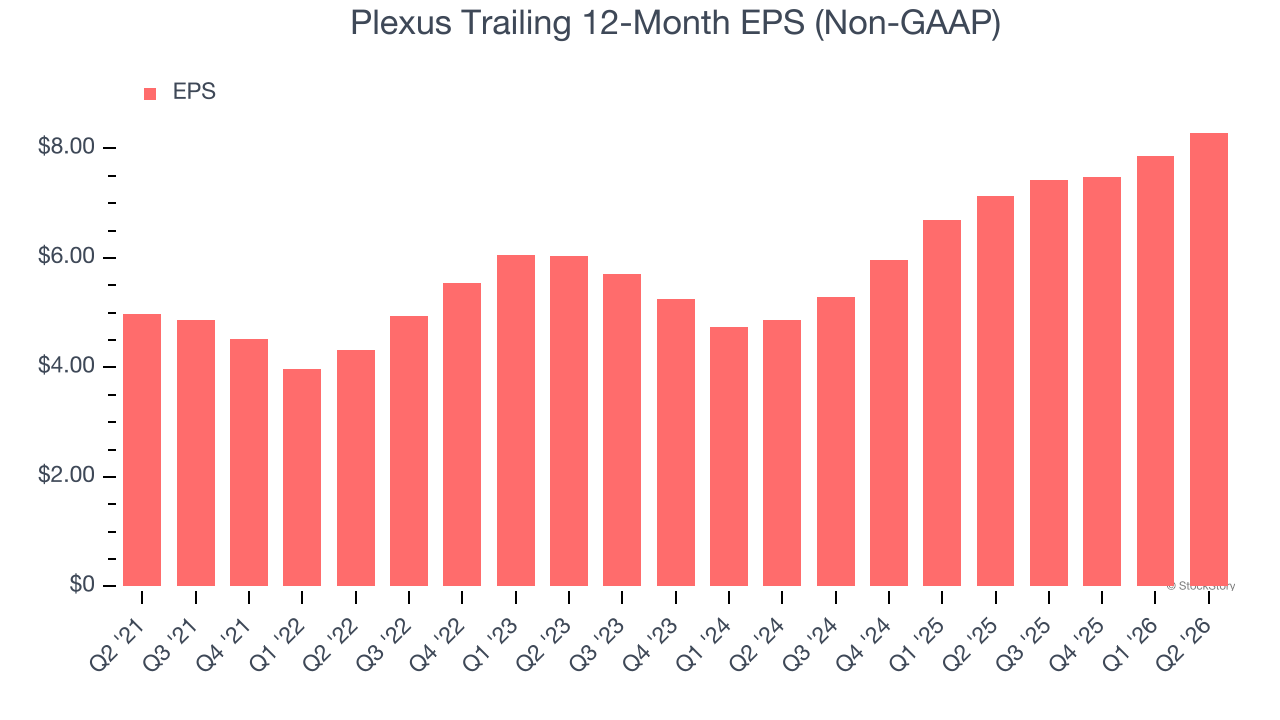
Plexus’s EPS grew at 10.8% compounded annual growth rate over the last five years, higher than its 6% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
Final Judgment
These are just a few reasons Plexus is a rock-solid business worth owning, and with its shares outperforming the market lately, the stock trades at 27.2× forward P/E (or $266.66 per share). Is now the time to initiate a position? See for yourself in our full research report, it’s free.
Stocks We Like Even More Than Plexus
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.